Introduction
Owning your first big bike is a thrilling milestone. Whether it’s the roar of the engine, the sense of freedom on the open road, or the sleek design that caught your eye, there’s no denying the allure of powerful motorcycles. But with great power comes great responsibility—and one of the most essential responsibilities for new riders is securing the right insurance.
While many see motorcycle insurance as a legal checkbox, it serves a far more vital purpose. For beginners especially, big bike insurance is a safeguard that protects you, your finances, and your ride from unexpected mishaps. In this guide, we explore why insurance is more than just a legal requirement—it’s a must-have investment for peace of mind and smart riding.
What Is Big Bike Insurance?
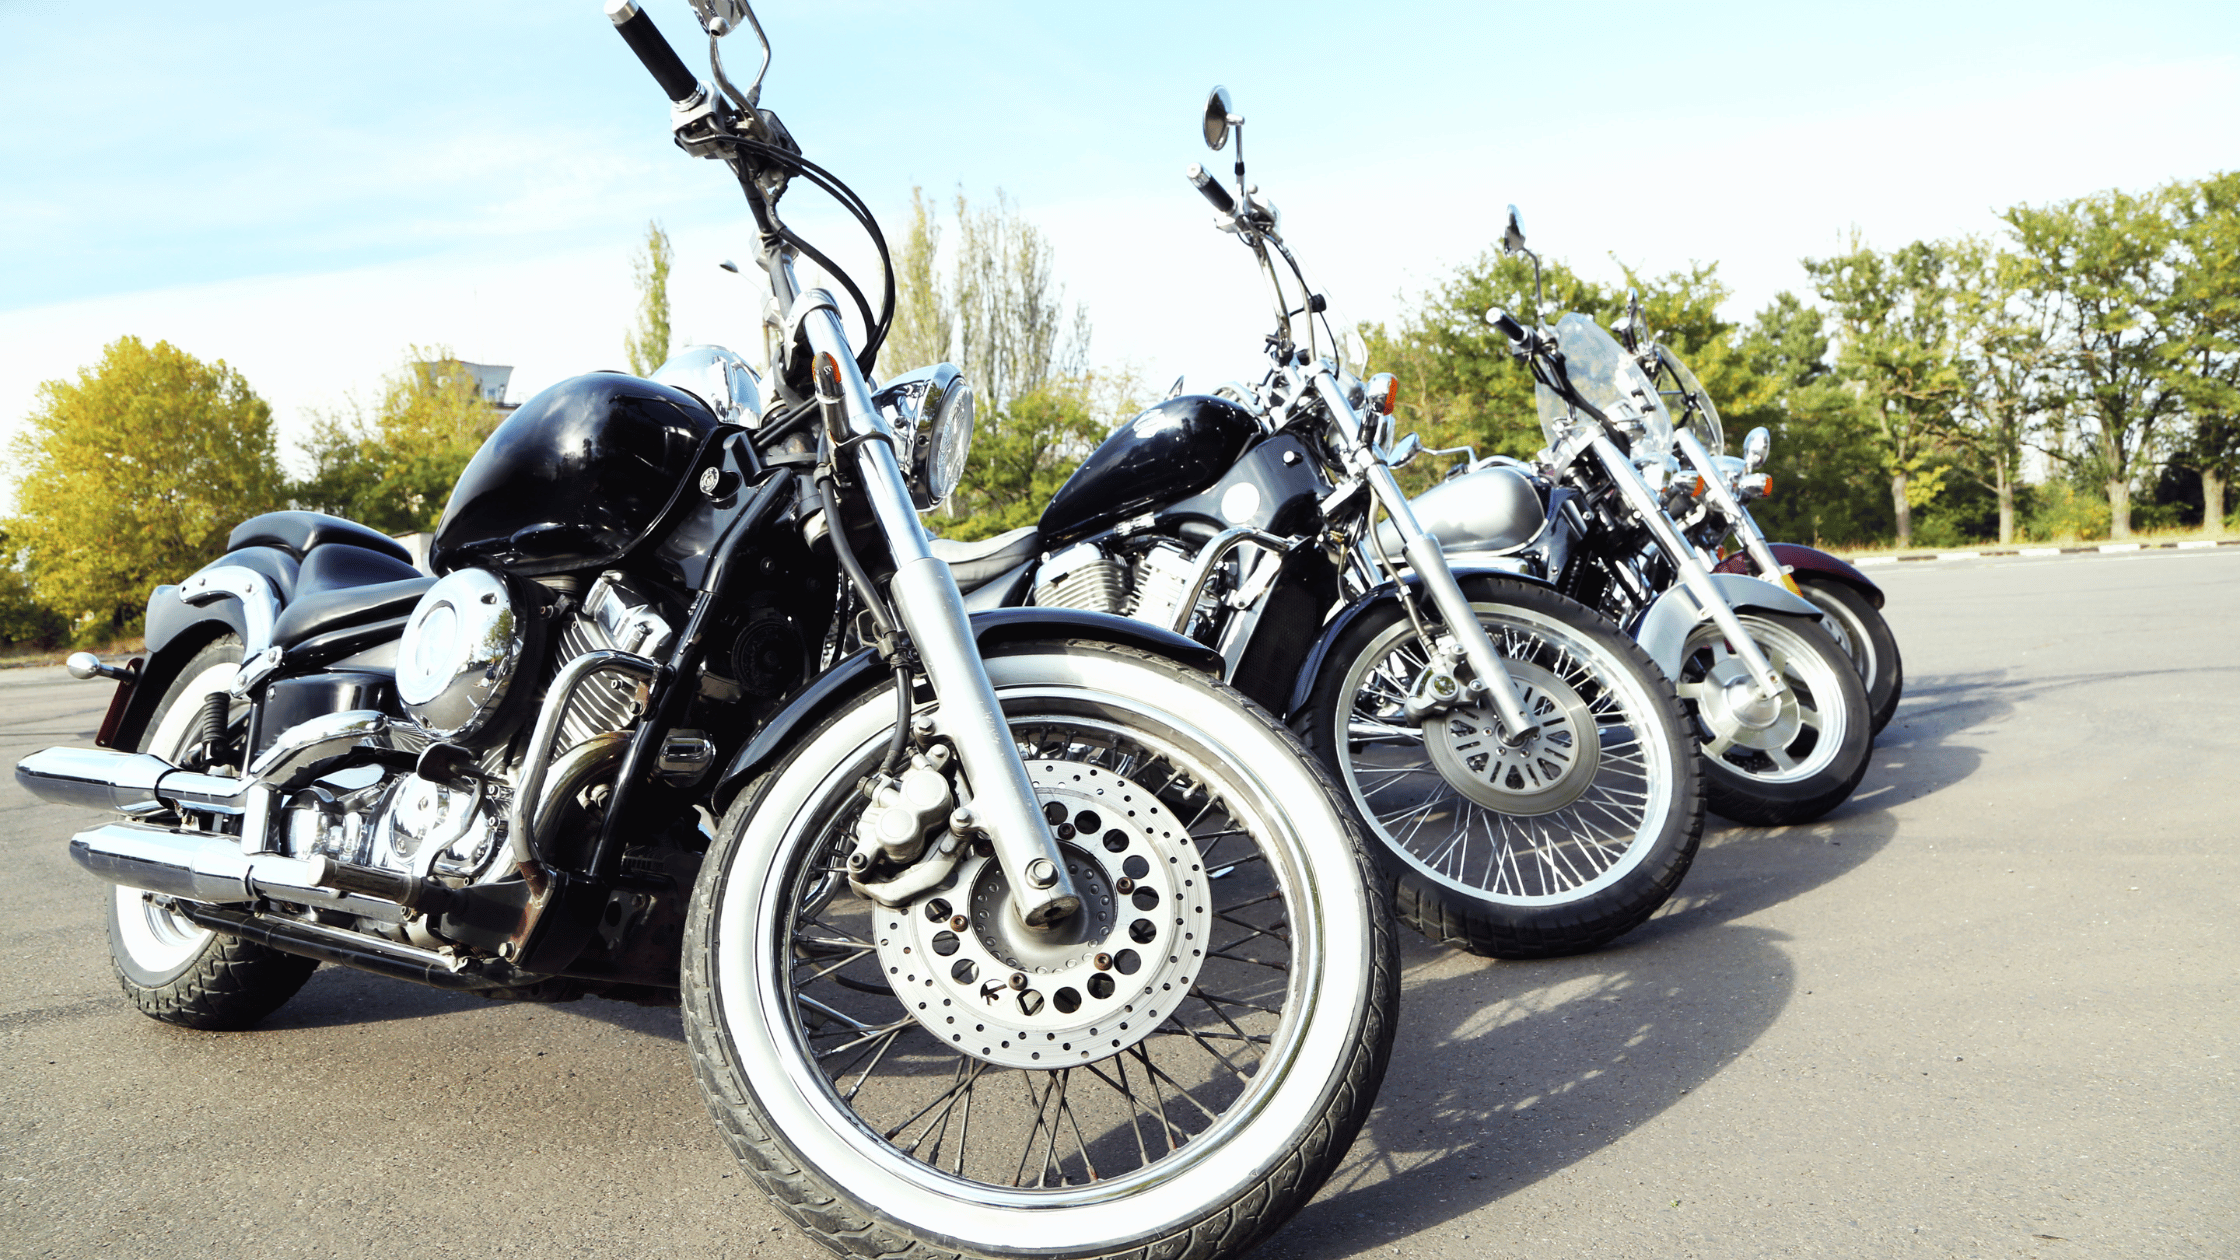
Big bike insurance refers to coverage specifically designed for motorcycles with larger engine capacities, usually over 250cc. These bikes are faster, heavier, and often more expensive than standard commuter bikes, which means they come with increased risks—both in terms of potential damage and liability.
Types of Motorcycle Insurance Coverage:
- Third-Party Only: Covers damage or injury you cause to others.
- Third-Party, Fire, and Theft: Adds protection for fire damage and theft.
- Comprehensive: Covers third-party damage, your own bike, personal injury, theft, and more.
In many countries, third-party coverage is the minimum legal requirement, but comprehensive insurance offers the most protection.
Why Insurance Is Critical for New Riders
1. Accidents Happen, Especially for Beginners
Even with proper training, beginner riders are more prone to mistakes on the road. Reaction times, maneuvering, and confidence all take time to build.
Insurance helps cover:
- Bike repairs after a crash
- Medical expenses for injuries
- Liability for damage to property or other vehicles
Without insurance, you could face enormous out-of-pocket costs after even a minor accident.
2. Big Bikes Mean Bigger Repair Bills
Performance motorcycles often come with specialized parts, advanced electronics, and expensive bodywork. Repairs can easily cost thousands of baht or dollars.
Comprehensive coverage protects against:
- Scratches and dents
- Mechanical failures
- Vandalism or accidental damage
For beginners still learning bike handling, this protection can be a financial lifesaver.
3. Theft Risk Is Real
Big bikes are attractive targets for thieves due to their high resale value and demand for spare parts.
Insurance provides:
- Compensation for stolen bikes
- Coverage for attempted theft damage (e.g., broken locks or ignition)
- Option for GPS-based tracking discounts in some policies
4. Weather and Road Hazards
Unlike cars, motorcycles are highly vulnerable to road conditions. Slippery roads, potholes, or sudden storms can cause serious accidents, especially for new riders.
Comprehensive policies can help cover weather-related incidents or damage caused by road hazards that are beyond your control.
5. Legal and Financial Protection
Should you be involved in a collision where another person is injured or their property is damaged, the legal costs and compensation could be significant.
Insurance helps with:
- Legal representation
- Medical expenses for third parties
- Settlements and court fees
For new riders, this safety net provides peace of mind when building road experience.
6. Support Services and Roadside Assistance
Many insurance providers offer value-added services like roadside assistance, towing, or emergency fuel delivery. These can be especially helpful for beginners who may not yet be comfortable handling breakdowns alone.
7. Some Financing or Leasing Deals Require It
If you bought your bike on finance or are leasing it, the provider might require you to have comprehensive insurance as a condition of the contract.
What to Look for in a Big Bike Insurance Policy
1. Coverage Scope
- Does it include personal accident cover?
- Are pillion riders included?
- Does it cover natural disasters or riots?
2. Premium vs. Deductible
- Choose a balance between monthly premiums and the deductible (the amount you pay when making a claim).
3. Claim Process
- How easy is it to file a claim?
- Does the insurer have a good reputation for claim settlement?
4. Network Garages
- Is there a wide network of authorized repair centers?
- Are genuine parts used in repairs?
5. Discounts and Add-ons
- No-claim bonus (NCB) for safe riding
- Theft tracking discounts
- Custom parts coverage
Tips for New Riders Shopping for Insurance
- Compare policies online to find the best value and coverage
- Be honest about your riding experience and usage (commuting vs. occasional)
- Take a certified safety course to qualify for premium discounts
- Consider bundle deals if you have other insurance needs (e.g., home or auto)
Conclusion
For beginner big bike riders, insurance is not just a legal formality—it’s a critical layer of protection that safeguards your safety, your finances, and your investment. While learning to ride and navigate new roads, having the right insurance means you can focus on building your skills with confidence.
From accident coverage to theft protection and legal liability, a well-chosen insurance policy ensures that one mistake doesn’t derail your riding journey. In the world of motorcycling, it’s not just about going fast or looking cool—it’s about riding smart. And that starts with being properly insured.